Three Critical Questions to Evaluate Before Claiming Social Security at 62
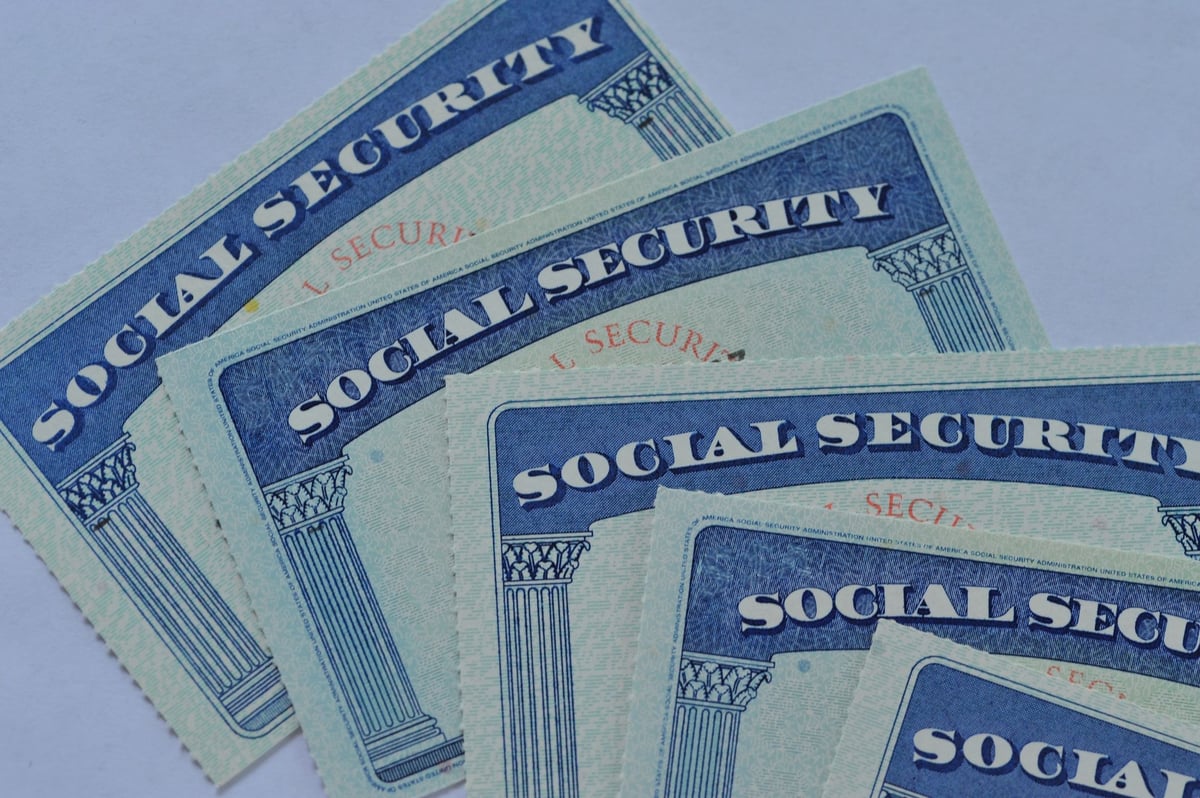
Deciding to take Social Security at age 62 locks in permanently reduced monthly payments, making careful financial planning essential for everyday households. Reviewing anticipated expenses, alternative income streams, and personal health outlook can help prevent costly retirement missteps.
 💳Personal Finance
Photo: Motley Fool
Key points
- Claiming Social Security at 62 permanently reduces monthly benefits compared to waiting until full retirement age.
- Retirement budgets often stay high as healthcare and entertainment costs offset commuting savings.
- Health status and family history help determine whether early filing maximizes or hurts lifetime payouts.
Evaluating the Trade-offs of Early Social Security Retirement Claims
Retirement planning involves a pivotal choice regarding when to begin collecting Social Security benefits. While individuals can start filing as early as age 62, doing so results in a permanent reduction in monthly payments compared to waiting until the full retirement age of 67 for those born in 1960 or later. Conversely, holding off past full retirement age yields an annual guaranteed 8% increase for life until age 70. For everyday investors and households approaching retirement, weighing the temptation of immediate cash against long-term financial security requires addressing three core questions.
Assessing Real Retirement Expenses and Alternative Income
Many future retirees assume yearly living costs will decline substantially once they stop working, but core expenses often remain steady or even climb due to healthcare and leisure activities. Drafting a detailed budget that incorporates irregular costs, such as home repairs and vehicle insurance, is vital to determine if a reduced Social Security check will suffice. Furthermore, retirees should evaluate outside income sources. For example, if a household requires $60,000 annually and expects $35,000 from savings and interest, Social Security must bridge the remaining $25,000 gap. Filing early is a mistake if it fails to generate that required difference.
Factoring in Personal Health and Longevity
Estimating life expectancy is arguably the most challenging part of retirement planning, yet personal health and family medical history provide essential clues. Claiming benefits at 62 can deplete total lifetime payouts for those who live a longer life, whereas individuals facing health challenges might actually maximize their total lifetime benefit by collecting early. What to watch next: Monitor any upcoming legislative debates regarding Social Security adjustments or adjustments to full retirement ages.
Source Motley Fool — fool.com/retirement/2026/11/14/planning-to-claim-social-security-at… ↗
Read next
 🧠AI Analysis
Real Assets Gain Traction as Traditional Bonds Struggle to Cushion Portfolios
Traditional fixed-income assets fell 2.69% through September 30, prompting everyday investors to reconsider the classic 60/40 portfolio structure by integrating real asse…
 🧠AI Analysis
FLEX LNG Posts Record Third-Quarter Revenue While Payouts Outpace Earnings
FLEX LNG delivered record revenue in the third quarter, though its net earnings fell short of covering the company's dividend distribution.
 💼Investing
Equinox Gold Positioned for Potential Re-Rating Following Orla Acquisition
Equinox Gold shares are drawing renewed investor interest following an upgrade to a strong buy rating, supported by a compelling valuation and the strategic impact of the…
 💼Investing
Cisco Shares Slide Over 6% Despite Record Revenue and Raised Guidance
Cisco Systems shares dropped more than 6% following a beat-and-raise quarterly earnings report as investors focused on decelerating product order growth and margin pressu…
 🧠AI Analysis
Dropbox Stock Performance: A Reassessment of Customer Retention
An analyst has revised their outlook on Dropbox (DBX), noting that the company's customer retention has exceeded prior expectations, despite recent underperformance compa…
 💼Investing
Anthropic Filing Highlights Natural Gas as AI's Power Bottleneck, Pointing to Infrastructure Plays Like Energy Transfer
An S-1 filing from Anthropic reveals that securing natural gas power is a major hurdle for artificial intelligence growth, turning the spotlight toward energy infrastruct…